Before sending rewards, HR and finance teams need a clear answer: are gift cards for employees taxable? In the United States, employee gift cards generally count as taxable pay. IRS Publication 15-B treats gift cards as cash equivalents and excludes them from the de minimis rule, regardless of amount.
Are gift cards for employees taxable?
Employee gift cards are cash-equivalent fringe benefits. Under IRS Publication 15-B (2026), cash equivalents do not qualify for the de minimis exclusion. Employers generally report taxable employee fringe benefits as wages.
A $20 store card, $50 prepaid Visa card, or $200 multi-brand card gives the employee a stated reward value.
The IRS separates cash equivalents from qualifying non-cash property. That distinction determines whether an employee reward fits a de minimis or achievement-award exclusion.
Why gift cards count as cash equivalents
Employee gift cards are cash equivalents under IRS Publication 15-B (2026). Their form, rather than their amount, keeps them outside the de minimis exclusion.
A quick comparison helps separate taxable employee rewards from non-cash items that need further review:
| Reward given to an employee | Federal treatment | Payroll question |
|---|---|---|
| Cash | Taxable wages | Include the value in employee compensation |
| Gift card or gift certificate | Taxable wages | Include the card’s value in payroll records |
| Low-value non-cash item | Review de minimis conditions | Confirm that the item is occasional and not cash-equivalent |
Take a 40-person team receiving $25 cards. The employer has assigned $1,000 in employee rewards, with $25 recorded for each employee.
IRS Publication 15-B (2026) applies the employee-benefit exclusions according to the reward’s form and the relevant conditions.
Does the de minimis rule cover employee gift cards?
No. IRS Publication 15-B (2026) says an employee gift card remains a cash equivalent even when its value is low.
The rule covers occasional benefits whose value would be unreasonable or administratively impractical to account for. A low-value, non-cash item still requires review of its frequency, value, and form.
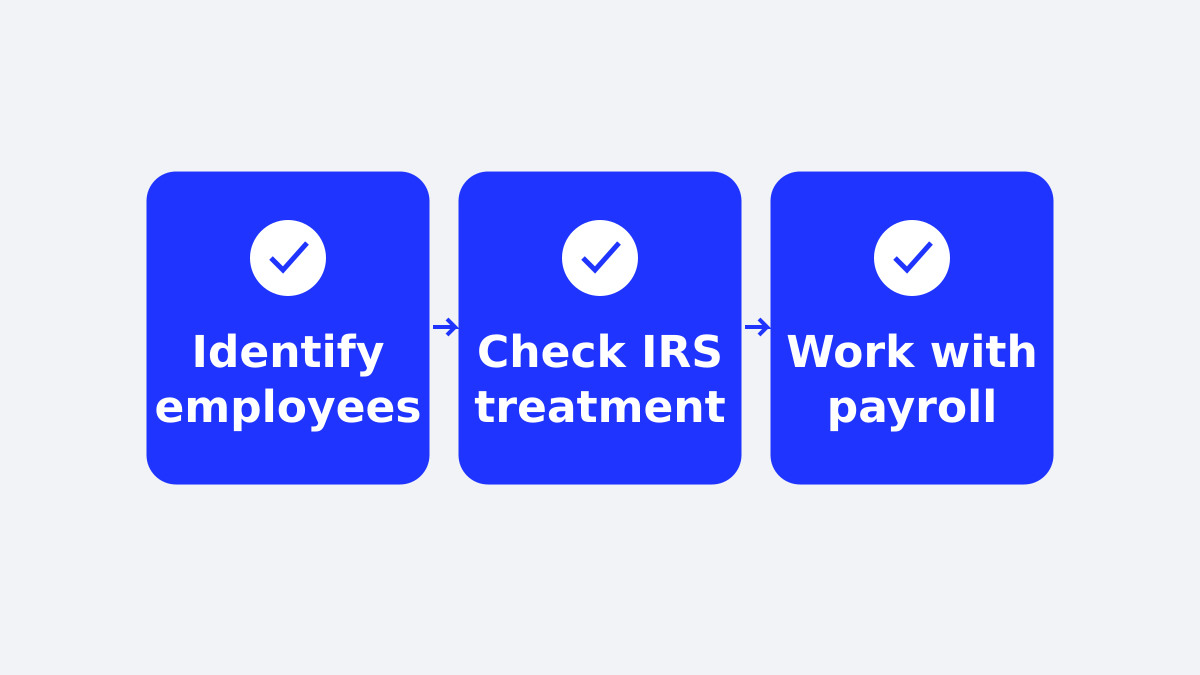
For each employee reward, note who receives it, what form it takes, which exception is relevant, and what payroll needs.
- Identify the recipient. Employee rewards follow payroll rules that differ from gifts to customers, contractors, or research participants.
- Identify the format. Cash, gift cards, and gift certificates are cash or cash equivalents.
- Check the exception. A non-cash benefit still needs to meet the applicable de minimis or achievement-award conditions.
- Send the details to payroll. Include the employee’s name, reward value, and date of delivery.
A non-cash employee item must meet the applicable de minimis or achievement-award conditions.
Are employee Christmas gifts tax deductible?
Employee gift cards are taxable wages for the employee under IRS Publication 15-B (2026). Employer deductibility is separate: IRS Publication 334 (2025) requires an ordinary and necessary business expense, reasonable pay for services performed, and proper tax-year timing. Those conditions do not guarantee that every employee gift card is deductible.
IRS Publication 15-B (2026) lists deduction limits for qualifying employee achievement awards: $400 for awards that are not qualified plan awards and $1,600 for all awards. Those limits do not automatically apply to every employee gift.
For a holiday reward, separate these questions:
- Employee treatment: Is the reward taxable wages to the employee?
- Employer deduction: Does the payment qualify as a deductible business expense under the employer’s facts?
- Award classification: Does the reward meet the requirements for an achievement award?
- Documentation: Can the employer show who received the reward, its value, and why it was provided?
Confirm the employer-side treatment with the company’s tax preparer before recording the expense.
For ideas that fit different budgets and occasions, compare the employee gift card options after confirming the payroll process.
Are employee recognition awards taxable?
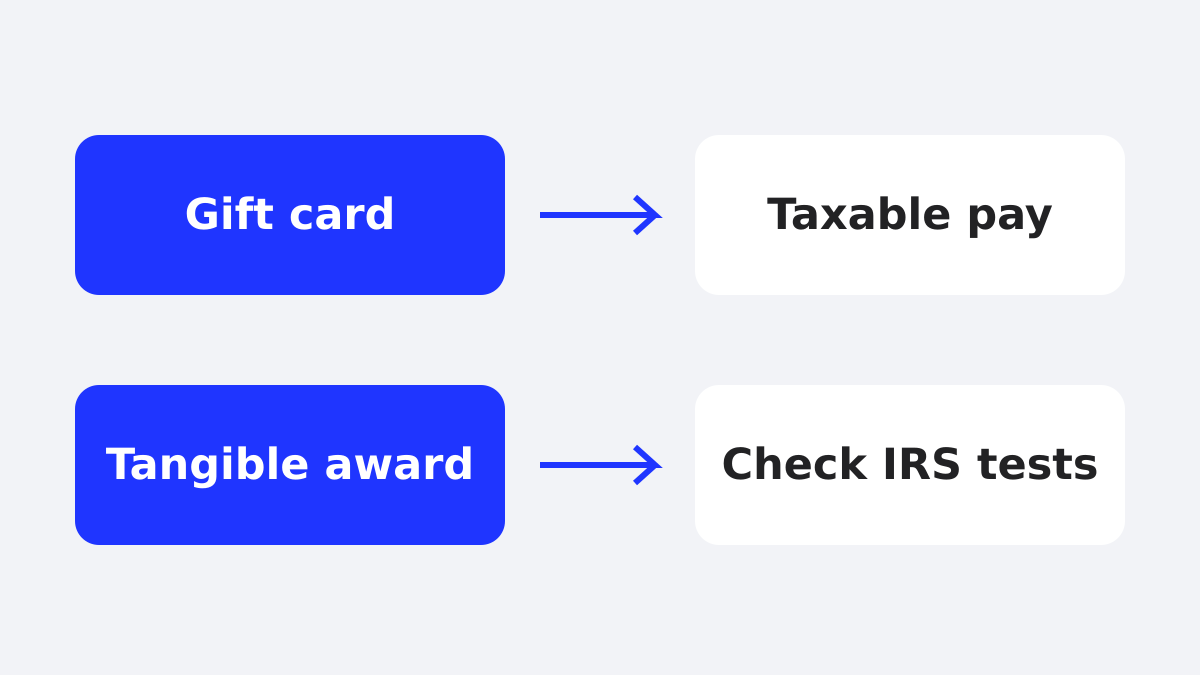
An employee recognition award is taxable wages when it is cash, a gift card, a gift certificate, or another cash equivalent. IRS Publication 15-B (2026) gives a different exclusion to certain qualifying length-of-service and safety awards.
The award exclusion requires tangible personal property, a meaningful presentation, and conditions that do not create a significant likelihood of disguised pay. A gift card does not meet the tangible-personal-property condition.
Compare the awards:
| Recognition reward | Treatment under the award rule | Condition to review |
|---|---|---|
| Gift card for a 10-year anniversary | Taxable wages | Cash equivalent, so the exclusion does not apply |
| Watch for a 10-year anniversary | Can qualify for exclusion | Must meet the award requirements |
| Cash safety bonus | Taxable wages | Cash does not qualify as tangible property |
The watch still requires review of the achievement-award conditions. The gift card remains taxable wages for the employee.
Can an employer give a gift to an employee?
An employer can give gifts to employees. IRS Publication 15-B (2026) excludes some occasional, low-value non-cash benefits from the employee’s wages when the applicable conditions are met.
Choose the reward format before announcing the program. A written review can record the business purpose, the payroll owner, and the information managers must provide.
A corporate gift policy can define:
- Which rewards managers can request.
- Which rewards require payroll review.
- What information the sender must provide.
- Who confirms the employee’s value and delivery date.
- How recognition awards are separated from ordinary bonuses.
If the company sends gift cards, maintain one list of recipients, values, and send dates. That record supports the payroll handoff and helps finance reconcile the program.
Use the Giftronaut sending guide to review the steps for choosing a branded gift card or a Choice Card and preparing the recipient list. Once you choose the reward, check the payroll treatment before sending it.
What HR should confirm before sending rewards
HR should confirm the recipient type, reward format, value, send date, and payroll owner before an employee gift card goes out.
Use this handoff:
- Build the recipient list: include employees only, with names that match payroll records.
- Record each value: capture the card amount assigned to every employee.
- Record the send date: note when the reward was delivered or made available.
- Flag the format: identify gift cards as cash-equivalent employee rewards.
- Confirm payroll handling: ask the payroll team how the value enters the relevant pay run.
Keep employee rewards separate from customer gifts, contractor payments, and research incentives.
Why gift cards are still a practical employee reward
Taxable treatment does not prevent an employer from giving an employee a gift card. The reward can still be useful when the company has a clear payroll process.
Before the next holiday, recognition, or milestone send, have payroll approve the process first. Then choose the reward, capture the recipient details, and send the list through the agreed workflow.
Frequently Asked Questions
Is a $25 gift card taxable income for an employee?
A $25 employee gift card generally counts as taxable pay. IRS Publication 15-B treats employee gift cards as cash equivalents, regardless of amount.
Are holiday gifts to employees taxable?
A holiday gift card generally counts as taxable pay. IRS Publication 15-B treats qualifying occasional, low-value non-cash benefits differently.
Are employee recognition awards taxable when they are gift cards?
A recognition award paid with a gift card generally counts as taxable pay. IRS Publication 15-B limits the achievement-award exclusion to qualifying tangible personal property.
Can employers give employees tax-free gifts?
Employers can give employees non-cash gifts that meet a de minimis or achievement-award exclusion. IRS Publication 15-B excludes cash and cash equivalents, including employee gift cards, from the de minimis exclusion.
Are employee gift cards deductible for the business?
Employee gift cards are not automatically deductible for the business. IRS Publication 334 sets conditions including an ordinary and necessary expense, reasonable pay for services performed, and proper tax-year timing. Those conditions do not guarantee a deduction for every employee gift card.