Are Christmas gifts for clients tax deductible, and what's the IRS limit per client? For US businesses, IRS Publication 463 (2025), Chapter 3 generally limits the deduction for gifts to nonemployee clients and contacts to $25 per recipient per tax year. The same publication treats ordinary packaging and mailing costs as incidental when they add no substantial value. It also describes a narrow exception for widely distributed identical promotional items costing $4 or less that carry permanent business identification.
Are Christmas gifts for clients tax deductible?
IRS Publication 463 (2025) applies the annual business-gift deduction limit to direct and indirect gifts. When a company gift is intended for particular individuals, identify the people who received it in your records.
How does the $25 client gift limit work?
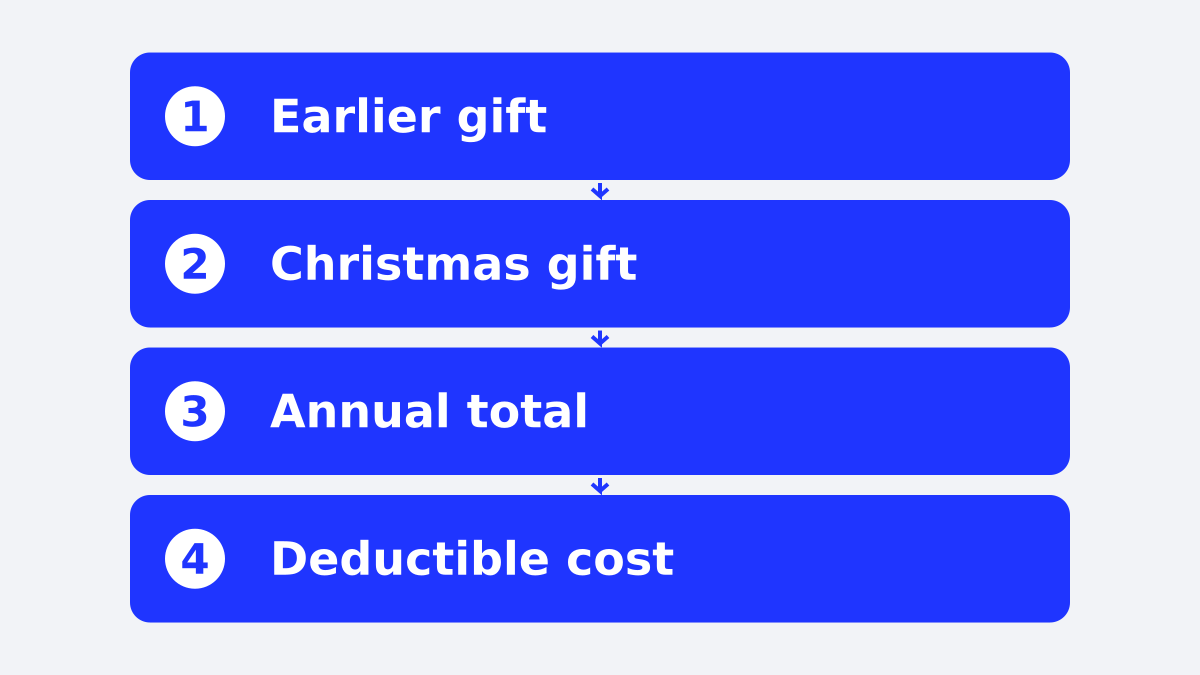
Record the gifts given to one recipient across the tax year before calculating the deductible amount. This example uses two gifts to the same client.
| Record | Example | Amount paid |
|---|---|---|
| Earlier client gift | $15 gift card to Jordan | $15 |
| Christmas client gift | $25 gift card to Jordan | $25 |
| Annual total | Two gifts to Jordan | $40 |
Take a business that sends nonemployee client Jordan a $15 thank-you gift in July and a $25 Christmas gift in December. Under IRS Publication 463 (2025), the business paid $40 during the year, but the federal business-gift deduction for Jordan is capped at $25.
For a different nonemployee client, the business sends one $20 gift. Under IRS Publication 463 (2025), the deductible amount for that recipient is $20 if the expense otherwise qualifies as a business gift and the records support its business purpose.
Use a recipient column in the tracker so earlier gifts are easy to locate.
Do packaging and mailing costs count toward the limit?
For gifts to nonemployee recipients, ordinary wrapping, mailing, and similar costs do not count toward the $25 limit when they add no substantial value. IRS Publication 463 (2025) treats those expenses as incidental costs rather than part of the gift amount.
Keep the costs visible in your records anyway. A receipt that separates the gift value from postage and packaging gives your finance team a clearer audit trail.
The distinction is about ordinary delivery costs. Do not assume that every extra service or presentation expense is automatically incidental. When a cost adds substantial value, ask a tax professional how it should be treated.
A practical record can separate the order into four fields:
- Recipient and company.
- Gift value.
- Packaging or mailing cost.
- Business purpose and date.
That structure gives your finance lead the information needed to review the annual limit without reconstructing the order from email threads.
What if the gift goes to a company instead of a person?
A gift addressed to a company can still be treated as an indirect gift to the identified people who receive it. IRS Publication 463 (2025) says the $25 limit applies when a gift to a company is intended for identified people.
The recipient record matters. “ABC Company” alone does not show whether the gift was for one named contact, several people, or the company generally.
For client gifts, record the individual recipient whenever the gift is intended for that person. If several people at the same company receive separate gifts, create a separate entry for each person.
For a promotional item given to nonemployees, the IRS Publication 463 (2025) exception requires a cost of $4 or less, permanent business identification, and wide distribution of identical items. A branded item that misses any condition does not qualify for that exception.
The exception is narrow. It is not a general way to turn expensive client gifts into promotional items.
How do gift cards fit into the client gift limit?
If a tax professional confirms a client gift card qualifies as a business gift, enter its value in the recipient’s annual record. Apply the limit using IRS Publication 463 (2025).
For your own gift tracker, note who received the gift, how much you paid, when it was given and the business reason. Keep a purchase record to help answer questions later.
A per-client tracker can use these columns:
| Column | What to record | Why it helps |
|---|---|---|
| Recipient | Name and company | Connects the gift to a person |
| Date and value | Purchase date and card amount | Builds the annual total |
| Purpose | Thank-you, holiday, or business relationship | Documents the business reason |
Record the amount paid, the intended recipient, and the business purpose. Ask your tax adviser whether the card qualifies before treating it as deductible.
What records should a business keep?
For gifts to nonemployee recipients, keep records showing the business purpose, recipient, date, and expense. IRS Publication 463 (2025) identifies those details as documentation for business gifts.
A practical recordkeeping checklist includes:
- Nonemployee recipient’s name and company.
- Gift amount and type.
- Purchase date and expense record.
- Business purpose.
- Receipt, invoice, and payment record.
- Packaging or mailing cost shown separately.
- Notes about earlier gifts to the same recipient.
Review the list before the order goes out, not after the holidays. A last-minute spreadsheet assembled from memory is where duplicate recipients and missing business purposes appear.
For large sends, one row per recipient is easier to review than one row per vendor invoice. If the business sends the same value to many contacts, the recipient list still needs to remain available.
Are employee gift cards treated the same way?
No. Gift cards given to employees are cash equivalents, not the same type of business gift as a client gift to a nonemployee. IRS Publication 15-B (2026) states that cash and cash equivalents, including gift cards, are not excludable as de minimis employee fringe benefits regardless of amount.
For a US employee, taxable fringe benefits generally go on Form W-2 under IRS Publication 15-B (2026). Have payroll handle the gift card separately from client gifts. Do not place employee recipients in the same client-gift tracker or apply the $25 nonemployee gift rule to them.
For employee gift questions, see the employee gift tax section in Giftronaut’s gift card taxation hub. The scope there is employee gifts, while this article focuses on clients and other business contacts.
How can a business organize a client Christmas send?
Start with a recipient-level tracker, then review the order before sending. IRS Publication 463 (2025) sets a $25 per nonemployee recipient deduction limit, not a universal holiday spending limit. Separate gift value, incidental costs, nonemployee recipient identity, and employee payments.
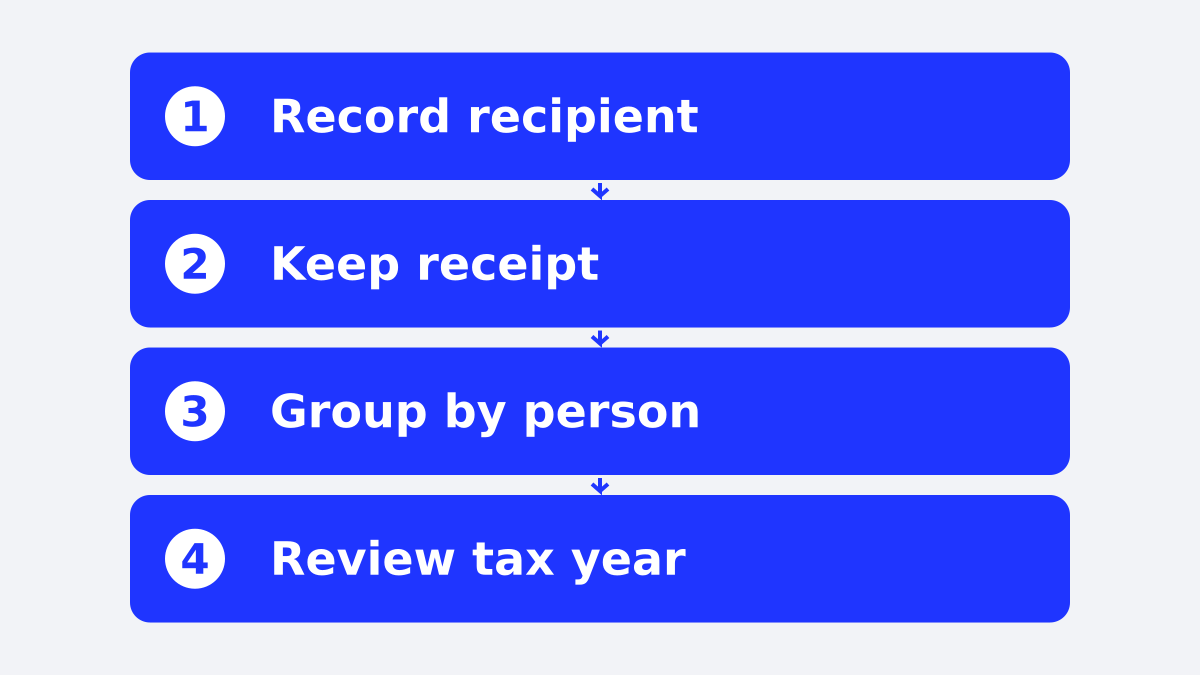
Use this sequence:
- Export the intended client list.
- Remove employees and other recipients that need separate treatment.
- Search the current tax year for earlier gifts to each person.
- Add the proposed Christmas gift value.
- Flag totals above $25 for finance review.
- Save the receipt, purpose, and delivery record.
- Ask a tax professional about exceptions or special rules.
The Giftronaut one-time order guide explains how to review an order before sending. Use a recipient-level record alongside the order to give your tax adviser the information they need.
Prepare the client gift order in Giftronaut
Before placing the order, match each amount and delivery detail to your recipient list. The Giftronaut order guide shows how to prepare and review orders. Keep your tax records separately from the order.
Check each client’s gift total before sending
I’d start with the recipient column. It makes it easier to find earlier gifts and explain the total. If you still need a gift idea, start with the client holiday gift guide.
Frequently Asked Questions
Can I write off Christmas gifts to clients?
US businesses can generally deduct client gifts to nonemployees, subject to the $25 per recipient per tax-year limit in IRS Publication 463 (2025). Keep the recipient, date, amount, and business purpose in the records.
What records should a business keep for client gifts?
For a nonemployee client gift, keep the business purpose, recipient, date, and expense records identified in IRS Publication 463 (2025). A receipt, invoice, payment record, and separate packaging or mailing entry can support that review.
Do gift cards count as business gifts?
For the rules on qualifying business gifts, see IRS Publication 463. For a specific client card, keep the purchase record and ask your tax adviser how it should be classified. Employee gift cards follow separate payroll rules under IRS Publication 15-B.
Does the $25 limit apply to each client company or person?
The limit applies per recipient. A gift to a company intended for identified people can be treated as an indirect gift to those people under IRS Publication 463 (2025).
Are gift cards to employees tax-free?
Gift cards to employees are cash equivalents and are not excludable as de minimis fringe benefits under IRS Publication 15-B. Route employee gift cards through the appropriate payroll review instead.