Why does ACH take so long? The answer is that an ACH payment passes through several stages, and settlement is not always the same as funds becoming available. Cutoff times, banking days, payment details, and provider review can add separate delays.
Why does ACH take so long?
ACH takes time because approval is only the beginning of the payment process. Your bank must accept the instruction, submit it for processing, and send it through the ACH network before the receiving bank can post the funds.
For troubleshooting, separate five events:
- Initiation: You authorize the payment through your bank or payment provider.
- File submission: The originating bank sends the payment instruction for ACH processing.
- Network settlement: Participating financial institutions exchange and settle the payment.
- Receiving-bank posting: The recipient’s bank applies the payment to the account.
- Availability: The recipient can use the funds under the applicable account or provider rules.
These events may happen close together, but they are not interchangeable. A bank may show a payment as “sent” when it has accepted or submitted the instruction, not when the recipient can spend the money.
Nacha’s ACH Payments Fact Sheet describes same-banking-day, next-day, and up-to-two-day credit settlement. Network settlement is a different milestone from the provider’s account-availability estimate.
How does an ACH payment move between banks?
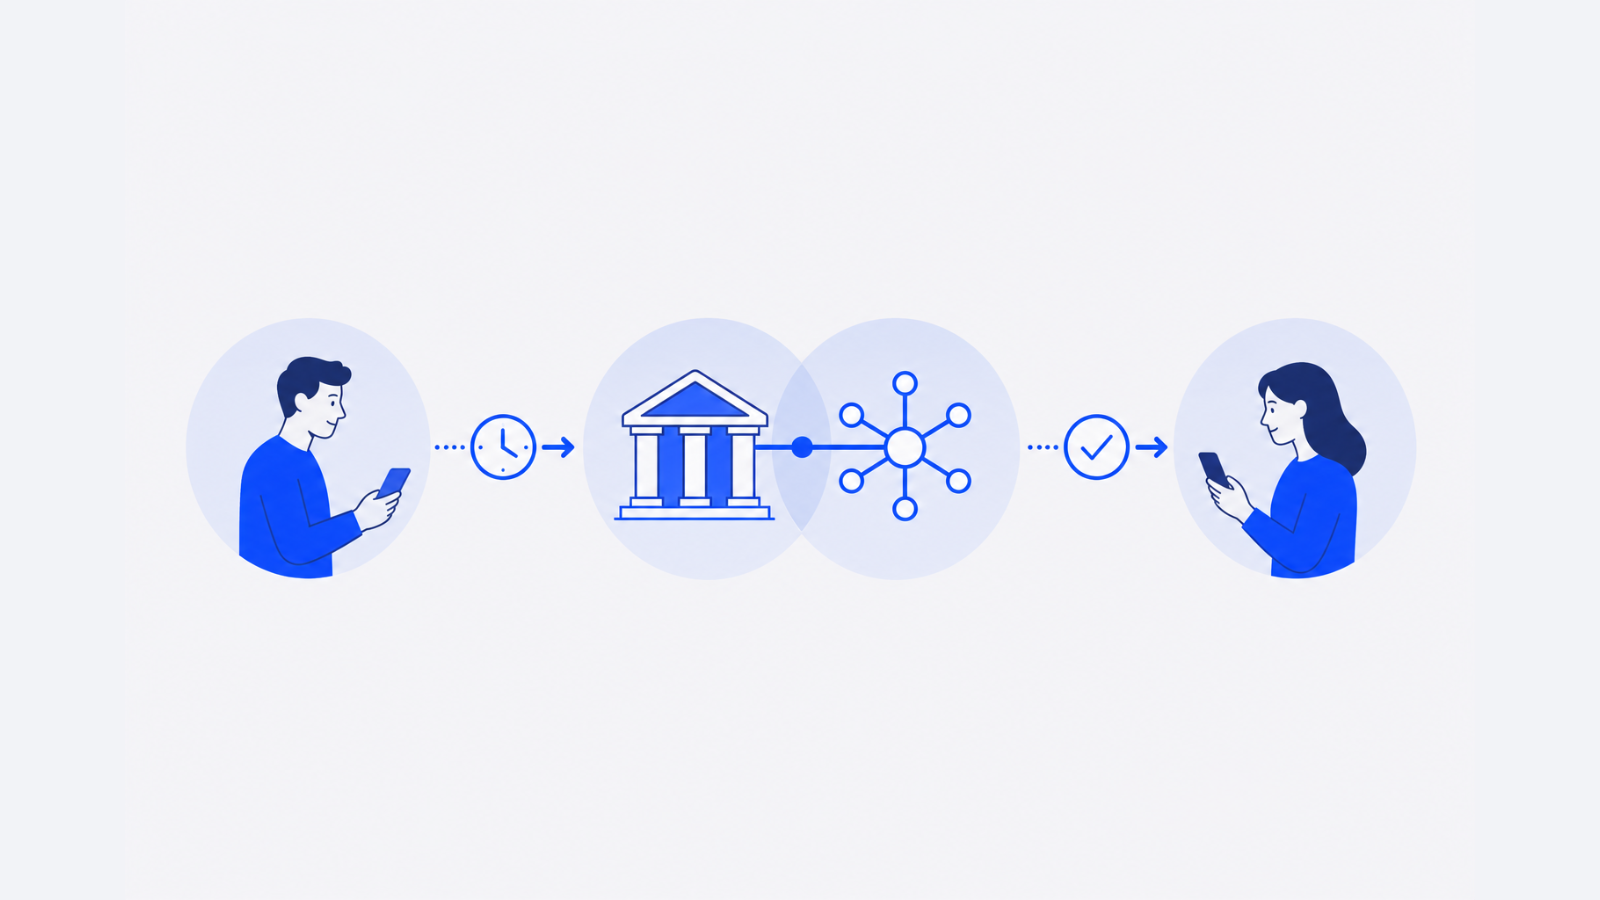
Nacha’s explanation of ACH payments identifies the originator, originating bank, ACH operator, receiving bank, and receiver. Each participant handles a different part of the movement, so a status at one stage may not describe the entire transaction.
| Participant | Role in the payment | Question to ask |
|---|---|---|
| Sender | Provides the amount, recipient details, and authorization | Did I submit the correct instruction? |
| Originating bank | Accepts, schedules, and submits the payment | Was it released into ACH processing? |
| ACH operator | Processes payment files between financial institutions | Has the payment reached settlement? |
| Receiving bank | Accepts and posts the incoming credit | Has the payment been posted or made available? |
The sender starts the process by approving an ACH instruction. The bank may immediately display a confirmation, but that confirmation does not necessarily mean the payment has left the bank.
The originating bank then schedules the instruction according to its processing procedures. The bank’s cutoff time can determine whether the payment enters an available processing window or waits for a later one.
The ACH operator processes files exchanged between financial institutions. Network settlement records the movement between banks, but it does not control every later posting or availability decision.
The receiving bank receives the credit and applies it according to its procedures. The account may show the payment quickly, or the bank may make it available under a separate schedule.
Different banks and services use these labels differently. Use the status definition supplied by the institution handling the payment, rather than assuming identical meanings across systems.
If you are funding a Giftronaut order, initiate the transfer using the current Giftronaut ACH and wire payment instructions. The payment instructions supplied by the recipient provider should take priority over a general ACH timetable.
How do cutoff times, banking days, and provider checks affect timing?
Cutoff times, non-banking days, incorrect details, and provider checks affect different parts of the process. Treating them as one generic “ACH delay” makes it harder to identify the next useful action.
Cutoff times
The payment-processing guide describes batch submission windows and cutoff times. If you submit an instruction after the bank’s cutoff, it may wait for a later window.
The relevant cutoff belongs to the bank or payment service accepting the instruction. Your local clock does not necessarily determine when the payment enters processing.
Check the confirmation, payment terms, or support information for the institution handling the transfer. Do not assume that an instruction created before midnight counts as submitted that day.
Weekends and federal holidays
Nacha states that ACH network settlement does not occur on weekends or federal holidays. A payment submitted near one of those periods may therefore wait for the next available settlement opportunity.
This does not mean every bank stops working on every related task. It means network settlement timing and ordinary account posting should not be treated as continuous, seven-day processing.
Count the relevant banking days from the actual send date. The date you created the instruction may be earlier than the date your bank released it.
Incorrect or incomplete details
The payment-processing guide describes incorrect account details and submission timing as possible causes of delay requiring intervention. A correct instruction removes one possible problem, but it does not guarantee immediate availability.
Compare the submitted details with the intended recipient before sending another payment. A duplicate transfer can create a second transaction while the first remains in progress.
Reviews and holds
The payment-processing guide notes that authorization issues or additional verification can delay processing. Ask your bank or provider whether such a check applies; do not assume every transfer has a hold.
Ask whether the delay concerns submission, settlement, posting, identity or payment review, or availability release. Those answers point to different responsible parties.
For Giftronaut-related payments, use its current payment instructions and support process rather than applying an assumed provider timetable. Keep the provider’s funding estimate separate from the network timetable.
How do you check a delayed ACH transfer?
Start with the actual send date and the last confirmed status. Then contact the party responsible for that stage instead of sending a second payment immediately.
| Possible delay | Next check | Responsible party |
|---|---|---|
| Instruction was created but not released | Ask whether the bank accepted and sent it | Originating bank |
| Cutoff affected processing | Check the bank’s applicable cutoff | Originating bank |
| Weekend or holiday intervened | Count banking days from the send date | Bank or provider |
| Details may be incorrect | Compare the submitted account information | Originating bank |
| Bank shows “sent” only | Request the current settlement status | Originating bank |
| Settlement is confirmed | Ask whether posting is complete | Receiving bank |
| Funds are posted but unavailable | Ask about availability rules or review | Receiving bank or provider |
| Expected window passed | Provide the payment reference for tracing | Bank and provider |
Use this sequence:
- Confirm the send date. Find the date the originating bank actually released the payment.
- Record the exact status. Save the wording shown by the bank, such as pending, submitted, sent, settled, returned, or held.
- Check the calendar. Account for weekends and federal holidays that affect network settlement.
- Verify the recipient details. Compare the submitted information with the payment instructions.
- Ask about availability. Confirm when the recipient can use the funds, not only when settlement occurred.
- Contact the correct party. Start with the originating bank if release or settlement is unclear.
- Share the transfer reference. Include the amount, send date, bank, recipient details, and status.
Are there faster options, and what are the tradeoffs?
Faster options may exist, but speed depends on eligibility, cutoffs, fees, and when the recipient can actually use the funds. Same Day ACH can support same-banking-day settlement when the payment and participating institutions meet the applicable requirements.
Nacha’s guidance distinguishes same-day settlement from next-day and up-to-two-day settlement. Same-day settlement is not a universal promise of same-day availability, because bank posting and provider rules remain separate.
| Option | Potential advantage | Tradeoff to verify |
|---|---|---|
| Same Day ACH | May settle during an eligible banking day | Cutoff, eligibility, and availability rules |
| Standard ACH | Familiar bank-to-bank process | Scheduled settlement windows |
| Wire transfer | Uses a separate transfer process | Bank requirements, cost, and recipient acceptance |
| Card funding | May provide another funding route | Processing fees, verification, and provider limits |
A wire may be appropriate when the receiving provider supports it and the bank’s requirements fit your deadline. It is not automatically cheaper or immediately available, so confirm the total cost and expected posting time first.
Same Day ACH may also be unsuitable if the payment is initiated after a cutoff, falls near a non-banking day, or requires a separate review. Ask the bank which service it is actually sending, not merely whether it supports “fast ACH.”
For a Giftronaut payment, use the current instructions supplied by Giftronaut and confirm the receiving method before switching rails. Do not assume that a different payment method removes provider review or makes funds available immediately.
A practical decision framework is:
- Deadline: Identify when the recipient must use the funds.
- Eligibility: Confirm that the bank and provider support the selected rail.
- Total cost: Include bank charges, provider fees, and any currency conversion.
- Traceability: Choose a method that provides a clear transfer reference.
- Availability: Ask when the recipient can use the funds, not only when settlement occurs.
For reward funding, compare the complete path from authorization through availability. Our bank transfer versus card funding guide explains that specific choice; this article focuses on diagnosing the bank-transfer stages.
Read ACH delays by their last completed stage
ACH is a sequence, not a single event. Identify the last completed stage, then contact the institution responsible for the next one.
That approach prevents duplicate payments and turns a vague delay into a specific question about submission, settlement, posting, or availability.

Frequently Asked Questions
Why does ACH take so long after my bank shows the payment as sent?
The bank may have released the instruction without completing settlement or recipient posting. Ask which stage remains incomplete.
Why does ACH take so long on weekends or federal holidays?
ACH network settlement does not occur on weekends or federal holidays. Processing resumes with the next available banking-day opportunity.
Why does ACH take so long when my account details are correct?
Correct details do not remove cutoff schedules, settlement windows, posting procedures, or provider availability rules. Ask for the current processing stage.
Why does ACH take so long for a provider payment?
Provider payments may involve settlement, posting, review, or availability steps. Use the provider’s current payment instructions and ask which step is pending.
Is Same Day ACH always available immediately?
No, Same Day ACH concerns eligible settlement timing, not necessarily immediate recipient availability. Cutoffs, bank posting, and provider rules still apply.
What should I provide when reporting a delayed ACH transfer?
Provide the send date, amount, transfer reference, originating bank, recipient details, and exact status. These details help the responsible party trace the payment.