Open loop gift cards use a payment network, rather than limiting spending to one retailer. They offer broader merchant choice, but the individual card’s country, transaction and balance rules still determine where a recipient can use it.
My friends’ group chat has never picked a restaurant on the first try. Someone always types “anywhere is fine,” and it never is: anywhere turns out to exclude the place with the two-hour wait, the place that closed in the spring and the one that only takes cash.
Open loop gift cards make a similar promise, and the exceptions live in the fine print. Choosing a reward gets awkward when you know what someone contributed better than where they shop. A store card makes that choice for them. A network card leaves more of it with the recipient, which helps until the card’s terms say otherwise. The useful comparison is between specific cards, not between the most generous claims about each category.
What is an open loop gift card?
An open loop gift card is a prepaid card with a payment network logo that can be used at merchants on that network. The issuer’s terms still apply to each purchase, so network acceptance and an approved payment aren’t the same promise.
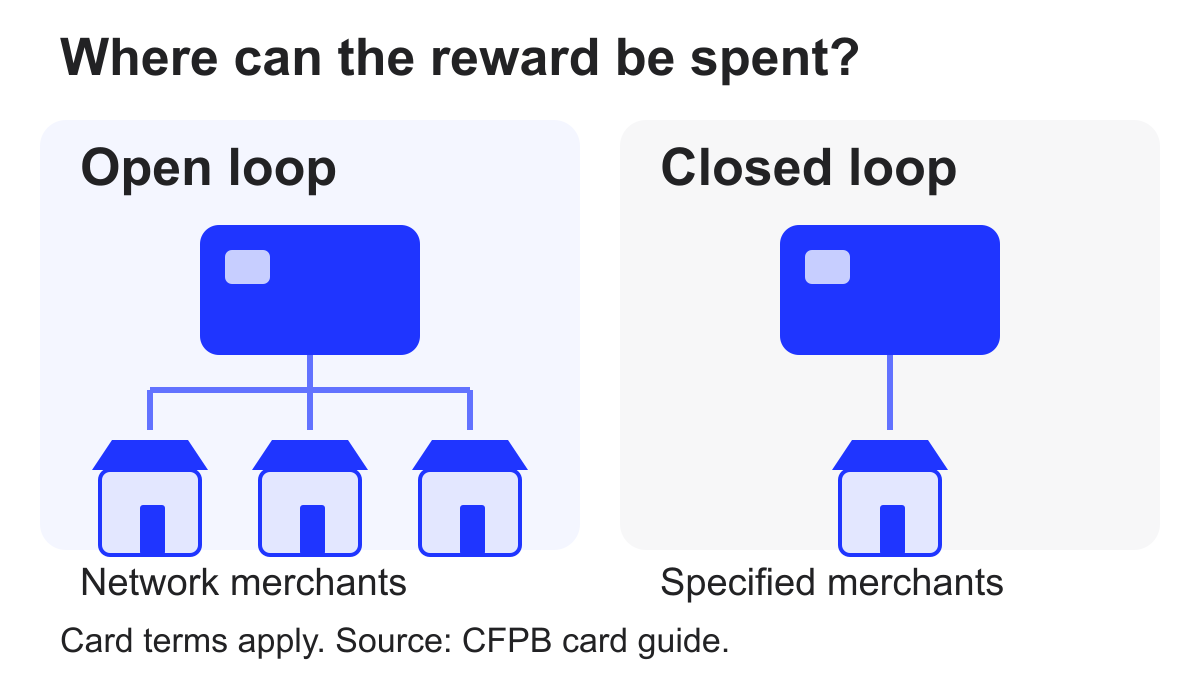
The Consumer Financial Protection Bureau’s prepaid card guide describes an open-loop card as one with a network logo that works anywhere that card type is accepted, and a closed-loop card as one you can use only at certain locations, such as a specific store or group of stores. It also notes that a gift card may carry a network logo or work only at certain locations, so the label tells you where a card can be spent, not what kind of product it is.
Open loop vs closed loop gift cards
Open loop gift cards work at merchants on a payment network, while closed loop gift cards work at one retailer or a defined group of merchants. Choose by how well you know the recipient’s habits, because neither format is better in every case.
| Decision | Open loop gift card | Closed loop gift card |
|---|---|---|
| Merchant choice | Participating merchants on the card’s network, subject to terms | The specified retailer or merchant group |
| Recipient preference | Useful when you don’t know a preferred retailer | Useful when the retailer is a confirmed fit |
| Details to verify | Country, transactions, fees, balance and expiry | Brand, country, permitted channels and expiry |
| Sender’s task | Explain the particular card’s conditions | Confirm that the recipient can use the retailer |
A closed loop card can feel more personal if the recipient is a regular at that brand. It also ties the reward to one retailer and one country: Giftronaut’s brand gift cards are country-specific, so an Amazon.co.uk card can’t be redeemed on Amazon.com in the United States.
A recipient-choice reward is a third route. Giftronaut’s Choice Card lets recipients pick their own brand and currency, and whatever they pick keeps its own rules, so a choice experience doesn’t turn every option into an open loop card.
If you’re still choosing a provider, the platform selection guide covers the wider decision.
How do open loop prepaid cards work?
An open loop prepaid card holds value loaded in advance and carries a network logo, so merchants on that network can accept it within that card’s terms. Prepaid describes how the value is funded, and open loop describes where the card can be accepted.
The CFPB adds two cautions: a prepaid card spends money loaded in advance while a credit card involves borrowing, even when both show the same network logo, and a gift card that looks like a prepaid card can fall under different protections.
For US programs, the CFPB’s gift card regulation sets definitions and exclusions, including one for loyalty, award and promotional cards. Its commentary gives the example of a company rewarding employees for job performance with a card marketed only to businesses, which may qualify for an exclusion. So don’t promise one expiry rule across every reward card: ask your provider which terms govern the card you’re sending.
Here’s the path a Giftronaut prepaid card takes from order to checkout:
- The sender orders the card, and the recipient gets a reward link by email, or by text to US and Canadian mobile numbers.
- The recipient opens the link and activates the card, with no account needed for the Global Visa Reward Card. The card number and PIN are generated at that moment.
- The recipient spends it online, in store or by phone wherever the card’s network and terms allow, and can add it to Apple Pay or Google Pay.
- For the global cards, the same reward link shows the remaining balance and transaction history.
Because the card number is generated when the recipient opens the link, nobody can spend it before then. The redemption explainer has the details.
The same logo can still carry different rules. Giftronaut’s three prepaid options show how, and the international Visa gift card guide matches each one to the recipients it suits.
| Giftronaut card | Where it works | Currency |
|---|---|---|
| US prepaid Visa | United States only | USD |
| Canada prepaid card (Visa or Mastercard) | Canada only | CAD |
| Global Visa Reward Card | Visa merchants in 225 countries | USD |
The Swype Global Mastercard also works internationally: online wherever Mastercard is accepted, and in stores that take tap to pay or manual card entry. Neither global card works in countries under US sanctions.
Beyond country, review these details one by one:
- Funding: Whether value is loaded once or can be topped up. Giftronaut’s global cards are single-load, and a card closes when its balance reaches $0.
- Country and currency: Where the card can be spent, which purchase types work and whether a conversion fee applies.
- Cash access: Whether ATM withdrawals or transfers are allowed. Neither Giftronaut global card works at ATMs or on peer-to-peer payment apps such as Venmo.
- Validity: The card’s expiry, which is a different date from the reward link’s claim deadline (the two dates explained). The Global Visa Reward Card is valid for 6 months from issuance, and Giftronaut’s product page lists 6 months to 3 years across its prepaid cards.
When a payment is declined, start with the card’s issuer. Visa’s support page tells cardholders to contact their issuer or bank to find out why a card was declined, so a decline alone doesn’t mean the whole network is unavailable.
Pros and cons of open loop cards
The main benefit of open loop cards is broader merchant choice, and the main drawback is that one broad category hides real differences between cards.
Broader choice reduces preference guessing. You can recognize a mixed group without collecting each person’s favorite retailer, which helps when the reward should say thank you without telling the recipient what to buy.
Fees come from different places. A network card isn’t automatically fee-free, so keep the sender’s cost and the recipient’s cost apart. On Giftronaut’s Global Visa Reward Card, USD purchases carry no fee, while non-USD purchases carry a 3% international fee plus a 3% FX fee, 6% in total, so a $50 purchase in another currency would cost $3 in fees. The card has no issuance, monthly or inactivity fees. The Swype Global Mastercard charges a flat $0.50 for purchases outside the United States. On the sender’s side, funding an order by credit card carries a 3% processing fee, and ACH and wire deposits carry none.
Limited balances need planning. A card can’t be topped up once it’s spent, because Giftronaut’s global cards are single-load, so encourage recipients to check the remaining balance before they choose a purchase. Whether a merchant lets someone split a payment between the card and another method is that merchant’s call, so don’t promise it.
Clear instructions still matter. Tell recipients where to find the card details, the card’s terms and a support contact. A message that says only “enjoy your gift” leaves people stuck if they have to complete a claim or activation step first.
When to use open loop cards for rewards
Use open loop cards when you don’t know where recipients shop or when they live somewhere with no local gift card. Choose a closed loop card if the brand is a confirmed fit, and a recipient-choice reward when you want people to pick for themselves.
Typical fits are one-off thank-yous for people whose habits you can’t know, such as survey participants, customers or a mixed team. Where a country has no local gift card, Giftronaut can still reward recipients there with a global card.
Before you order, settle four things:
- Country: Where the recipient lives and where they’ll spend.
- Purchase: What the reward is for, and whether the card supports that purchase online or in store.
- Terms: The card’s fees and validity.
- Support: What the recipient will be told and who they can ask.
Giftronaut’s prepaid card page lists the US, Canada and Global options with their currencies, validity and fees, so compare those entries instead of assuming one card’s rules cover another. Keep the approved card name, market and terms together with the order record, and recheck them when the program changes, so recipient support can answer questions about the card you actually sent.
Choose the card the recipient can actually use
The group chat still hasn’t picked a restaurant on the first try. These days I reply “anywhere where?” before I agree to anything, and I ask a gift card the same question before it goes out.
Open loop gift cards are useful because they leave more choice with the recipient. Keep that benefit by checking the exact card and telling recipients its conditions plainly. Start with their country and what they’ll buy, then pick the format that fits.
Frequently Asked Questions
Can open loop gift cards be used internationally?
Only when the specific card allows it. Giftronaut’s US and Canada prepaid cards work only in their own countries. Its Global Visa Reward Card works at Visa merchants in 225 countries, and non-USD purchases carry a 6% fee.
Are open loop gift cards always reloadable?
No. Reloading is a separate card feature, and Giftronaut’s Global Visa Reward Card and Swype Global Mastercard are single-load. Each card closes when its balance reaches $0.
Do open loop gift cards allow cash withdrawals?
Not necessarily. Neither of Giftronaut’s global prepaid cards works at ATMs or on peer-to-peer payment apps such as Venmo. Check the exact card’s terms before promising cash access.
Do open loop cards expire?
Each card’s terms set its validity. Giftronaut’s prepaid cards range from 6 months to 3 years, and the Global Visa Reward Card is valid for 6 months from issuance.
Are all prepaid cards treated like consumer gift cards?
No. In the United States, prepaid accounts and gift cards can fall under different rules, with exclusions for certain reward products.
What should a recipient check after a declined payment?
Check the balance and card terms, then contact the issuer using the card’s support details. The issuer can explain the transaction-specific reason.
Is a choice catalog the same as an open loop card?
No. A choice catalog lets the recipient select a reward; the selected reward may be a store card or another eligible product.